Popular Articles
 Risk
20.09.2026
Tail Risk: Portfolio Loss at 95% vs 99% VaR
This article explains tail risk using Value at Risk (VaR) levels at 95% and 99%, aimed at investors and risk-minded readers. It clarifies what VaR does and does not measure, why the gap between 95% and 99% can be much larger than expected, and how portfolio construction, correlations, and liquidity shape loss outcomes. You will learn how to interpret VaR, stress-test assumptions, and avoid common reporting traps.
 Risk
14.09.2026
Tracking Error: Active Risk in ETF Portfolios
Tracking error measures how much an ETF’s returns diverge from its benchmark. This matters for investors who expect “index-like” behavior, for people comparing active vs. passive funds, and for anyone using ETFs for risk budgeting. The article explains what tracking error means, why it rises, how it differs from active share and tracking difference, and how to check it using fund reports. Readers learn practical steps, common pitfalls, and realistic scenarios.
 Risk
08.09.2026
Liquidity Risk: Exit Cost at 1%, 5% and 10% Drawdowns
Liquidity risk describes what happens when you need to exit an investment but the market cannot absorb your order at the expected price. This article explains how drawdowns translate into exit costs at 1%, 5%, and 10%, with practical examples for investors and risk teams. You will learn the mechanics behind bid-ask spreads, market impact, forced selling, and liquidity buffers, plus a checklist to estimate exit costs and avoid common measurement errors.
 Risk
02.09.2026
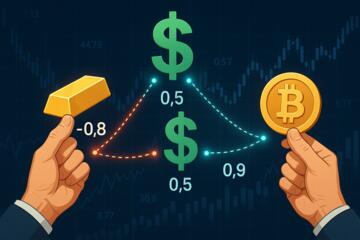
Correlation Breakdown: Stress-Test at 0.0 vs 0.8
This article breaks down what people mean by a “correlation breakdown” when a model or scoring system is stress-tested under two different correlation assumptions—0.0 (no relationship) and 0.8 (a strong relationship). It’s aimed at readers who come across health claims built on correlation, risk scores, or “symptom X leads to outcome Y” type links and want to judge how solid those claims really are. You’ll learn how to read the results when correlations shift, what kind of underlying data and validation should be shown, and how to do a quick sanity check yourself. It also highlights common pitfalls—like confusing correlation with causation or cherry-picking settings—that can make conclusions look convincing while being misleading.
 Risk
27.08.2026
Portfolio Beta: What Happens at Beta 0.8 vs 1.2
Portfolio beta is a simple way to describe how much your portfolio tends to move compared with a chosen benchmark (like the S&P 500). In this article, you’ll see what it really means when a portfolio has a beta of 0.8 versus 1.2—how those figures can translate into larger or smaller swings during rallies and selloffs, and what that implies for volatility and potential drawdowns. The guide also explains why beta isn’t fixed: it can shift as holdings change, market relationships evolve, or the time period used in the calculation differs. You’ll learn how to interpret beta with the right context, question the assumptions behind it, and stress-test your portfolio with realistic “what if” scenarios instead of depending on one headline number.
 Risk
21.08.2026
VaR vs Expected Shortfall: Which Measures Tail Risk?
Explore two common risk metrics used in finance: Value at Risk (VaR) and Expected Shortfall (ES). It helps readers who see these terms in reports, model documentation, or risk dashboards understand what each metric measures, how assumptions affect results, and why tail behavior matters. You’ll learn how to compare VaR and ES for losses beyond a threshold, how to interpret confidence levels, and which checks reduce misleading conclusions.
 Risk
13.08.2026
How to Stress-Test Your Own Portfolio
Stress-testing your investment portfolio means simulating how it performs under adverse conditions like market crashes or interest spikes. This guide helps individual investors anticipate risks, avoid common pitfalls, and sharpen their portfolio strategies with practical tools and concrete examples. Understanding stress tests bridges the gap between hoping for the best and preparing for the worst.
 Risk
07.08.2026
Managing Tail Risk When Correlations Break
Tail risk - extreme market events that cause outsized losses - poses a unique challenge when correlations break down unexpectedly. Portfolio managers, risk analysts, and institutional investors must confront the failure of traditional correlation assumptions that normally diversify risk. This article explores how to identify, assess, and mitigate tail risk during episodes when asset correlations suddenly change, supported by practical strategies, real examples, and a focus on actionable insights.
 Risk
01.08.2026
Sequence-of-Returns Risk and How to Blunt It
Sequence-of-returns risk impacts retirees who withdraw funds during market downturns, potentially depleting portfolios faster than expected. This article explains its causes and details practical strategies like bucket planning, dynamic withdrawals, and diversification to reduce exposure. It targets investors approaching or in retirement wanting to safeguard savings against volatile market returns.
 Risk
26.07.2026
How to Set a Rebalancing Band That Works
Rebalancing sounds simple - buy what’s down, trim what’s up - but doing it too often can rack up taxes, spreads, and trading fees, while doing it too rarely can let your risk drift way off target. This guide explains how rebalancing bands work: setting clear “guardrails” around your target allocation so you only trade when the portfolio meaningfully moves. Using real-world portfolio practices and data-driven examples, it shows how to choose sensible band widths, how bands differ for stocks vs. bonds (and taxable vs. retirement accounts), and the common mistakes that cause unnecessary churn or unintended risk.