Tail Risk and Correlations
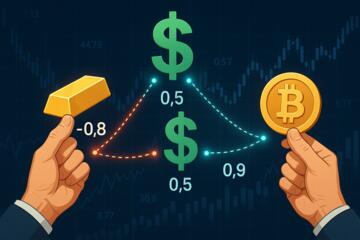
Tail risk describes rare but severe financial losses occurring beyond the usual market fluctuations. This risk magnifies during extreme events like the 2008 crisis or the COVID-19 market plunge when assets that typically move independently instead trend together. For example, during March 2020, global equity markets plummeted simultaneously, with correlations between sectors spiking from typical ranges near 0.4 to above 0.9.
Most portfolios rely on diversification driven by correlations being stable and moderate. If correlations remain low, losses in one asset class can be offset by gains or smaller declines elsewhere. But when correlations break—that is, sudden correlation shifts towards one—diversification benefits vanish. A 2019 study from the CFA Institute noted that during major stress periods, correlations increased on average above 0.8, exposing portfolios to unexpectedly large losses.
Understanding tail risk means recognizing that correlations are not fixed. They are dynamic, especially in crises, making monitoring correlation behavior fundamental for managing these large downside risks.
Struggles in Tail Risk
Most investors underestimate how often and how severely correlations break during market stress. They assume diversification works all the time. It does not. This results in underestimated portfolio risk and misguided hedging strategies, with losses that exceed planned risk limits.
For example, hedge funds relying heavily on equity-neutral strategies suffered when correlation spikes rendered their hedges ineffective. A classic case is Long-Term Capital Management in 1998. Unexpected macro shocks synced previously uncorrelated instruments, forcing liquidation under duress.
Ignoring tail risk linked to correlation shifts leads to cascading effects: liquidity dries up, margin calls intensify, and risk models fail. This domino effect transforms localized shocks into systemic crises.
Portfolio stress-testing rarely captures sudden jumps in correlations accurately, leading to blind spots in risk controls. The widespread consequence is unexpected drawdowns and performance divergence from forecasts during black swan events.
Approaches to Manage Tail Risk
Dynamic Correlation Tracking
Use rolling window correlation metrics updated daily or weekly to detect emerging shifts. This captures early signs of structural changes in asset relationships. Tools like Bloomberg PORT’s correlation matrix or Python libraries such as pandas and statsmodels can automate this process. A 30-day rolling correlation is a common choice, balancing responsiveness and noise reduction.
Stress Testing with Extreme Scenarios
Simulate portfolio outcomes under correlation spikes seen in past crises. Incorporate worst historical correlations rather than average ones. These tests reveal vulnerabilities not obvious from mean estimates. Risk engines from MSCI or RiskMetrics have pre-built modules for this, letting risk managers quantify potential tail losses under correlation stress.
Diversify Across Uncorrelated Factors
Shift part of the portfolio into assets with fundamentally different drivers—like inflation-linked bonds, real assets, or managed futures. These often decouple during equity market downturns. For instance, TIPS (Treasury Inflation-Protected Securities) rarely move in sync with stocks. Including about 10-15% allocation to such segments can lower tail vulnerability.
Use Options for Tail Hedging
Protect against abrupt swings by buying deep out-of-the-money put options on key indices or using volatility products like VIX futures. Although these have insurance costs, they pay off substantially in stress periods. The 2022 VIX spikes during geopolitical shifts highlight how volatility instruments serve as critical tail buffers.
Incorporate Regime-Switching Models
Models that detect changes between normal and crisis regimes allow for adjusted correlation inputs. For example, Markov switching models adapt correlation estimates based on observed volatility or macro indicators, delivering a more realistic risk profile. This method outperforms static correlation assumptions by reflecting market states dynamically.
Leverage Network Analysis
Map asset interconnections as networks rather than pairwise correlations alone. This reveals clusters that might jointly fail and contagion paths critical during crisis contagion. Network-based risk metrics expose structural weaknesses unrecognizable by traditional covariance matrices. Tools like Gephi and NetworkX help visualize these dependencies at scale.
Monitor Liquidity and Market Depth
Correlation breaks often coincide with liquidity squeezes. Watching bid-ask spreads, volume changes, and market depth alerts to deteriorating diversification benefits. Bloomberg’s liquidity metrics or proprietary dealer quotes give timely signals that can prompt defensive repositioning.
Adjust Position Sizing Dynamically
Lower allocations to correlated assets during volatility surges. Adaptive sizing responds to observed correlation and volatility spikes, limiting exposure when diversification fades. Quant traders often deploy volatility-timing overlays that rebalance not just on prices but risk characteristics.
Regularly Update Risk Models
Recalibrate risk factors and correlation matrices frequently with new data. Correlations in Q1 2024, for instance, can deviate greatly from those last year. Delayed updates compound model risk and impair decision-making. Risk departments should schedule updates at least monthly or after major market moves.
Tail Risk Handling Examples
During the 2020 COVID crash, J.P. Morgan Asset Management quickly shifted allocations toward Treasury bonds and gold after correlations surged. This move trimmed portfolio drawdown by approximately 18% compared to peers that remained equity heavy.
A midsize hedge fund using regime-switching models avoided the worst losses in the 2015 Chinese stock plunge. Anticipating correlation spikes, it increased put option hedges and reduced China-exposed equity weight from 12% to 5%, limiting losses to under 3% while the sector fell 15%.
Tail Risk Controls Checklist
| Control | Frequency | Metric/Tool | Outcome |
|---|---|---|---|
| Correlation tracking | Daily/Weekly | Rolling corr. matrix | Early sign detection |
| Stress tests | Quarterly | Historical crises data | Tail loss estimates |
| Options hedging | Ongoing | VIX, puts | Loss suppression |
| Regime models | Monthly | Markov switching | Adaptive risk view |
| Liquidity monitoring | Daily | Bid-ask spread, volume | Avoid illiquid traps |
Frequent Errors and Fixes
Trusting historic averages too much stands out as the biggest mistake. Correlations often jump unexpectedly, so relying on five-year static data blindsides risk assessment. Updating correlations frequently fixes this.
Ignoring liquidity shifts compounds tail risk. Shallow markets amplify price moves, negating standard hedges. The solution implies real-time liquidity tracking alongside price correlations.
Treating correlations as symmetric and linear also causes issues. Tail dependence tends to be asymmetric; assets spike together only in downturns. Copulas and nonlinear metrics capture this nuance better.
Over-hedging via options without evaluating cost drags depletes returns. Calibrating hedge ratios dynamically avoids paying for unused insurance.
Finally, failing to communicate tail risk clearly to stakeholders breeds unrealistic expectations. Risk managers should regularly illustrate downside scenarios shaped by correlation breaks.
FAQ
What triggers correlation breaks?
Sharp market stress, macro shocks, liquidity crises, and major geopolitical events often realign asset relationships abruptly.
How often should correlation be updated?
Updating at least monthly, and more often during volatile periods, captures evolving market conditions effectively.
Can diversification fail completely?
Yes, during extreme events correlations compress near one, nullifying diversification benefits temporarily.
Are volatility products effective hedges?
They are responsive tools but come at a cost; ideal as part of a layered tail risk defense.
Which models best signal regime changes?
Markov switching and Hidden Markov Models are widely used to detect regime shifts in correlation and volatility patterns.
Author's Insight
In my time managing multi-asset portfolios, watching correlations shift has been eye-opening. A presumed hedge can unravel overnight when correlations spike above 0.85 unexpectedly. Combining frequent data updates with scenario-driven stress tests helped me avoid large losses in 2020. The key is skepticism of static assumptions—adjust risk posture dynamically. Lastly, educating stakeholders on these hidden risks pays dividends when markets turn turbulent.
What to Remember
Tail risk intensifies when correlations break and diversification fails. Detect it early by tracking rolling correlations, stress-testing with worst-case assumptions, and including uncorrelated assets. Layer options and volatility products prudently for crisis buffers. Adapt risk models to evolving regimes and monitor liquidity closely. Avoid static models and communicate clearly. These steps improve resilience against unpredictable market tail events.