Income Yield Scenarios
“Yield” is a cash-flow rate, not a guarantee of what you will earn over time. A portfolio showing a 6% trailing yield can still deliver a lower total return if prices fall, dividends get cut, or interest rates move against you. The gap between yield and total return widens when the portfolio holds assets with credit risk, call risk, or duration risk. This article frames three target scenarios—4%, 6%, and 8%—and shows what must be true for each to be plausible.
In practice, investors often mix up three different measures: distribution yield (cash paid), SEC yield (for money-market and bond funds, depending on the product), and total return (price change plus income). For example, a bond fund can pay a steady monthly distribution while its NAV declines when yields rise. That pattern can look like “income” while the account value quietly erodes, which matters when you plan withdrawals.
To make the scenarios concrete, assume you want income for spending and you also want the portfolio to keep its purchasing power. That means you must track not only the cash rate but also the probability of drawdowns and the likelihood of income reductions. The scenarios below treat yield as a starting point and then ask what risks typically sit underneath.
Common Misreads And Dependencies
People often treat yield as a stable feature of a portfolio, then react late when distributions change. A high yield can be a warning label: it may reflect credit stress, falling bond prices, or a temporary structure that later resets. Even when distributions stay level, the underlying risk can shift from “income risk” to “principal risk,” which shows up during market drawdowns.
Yield targets also depend on supporting technologies in the investing process: reliable account-level reporting, accurate tax lot tracking, and disciplined rebalancing rules. If your brokerage statements don’t match your assumptions, you can misjudge whether the portfolio is actually producing the cash you think it is. I’ve seen investors use a spreadsheet built in 2022 and never update it after switching from one fund share class to another; the yield line looked fine, but the tax treatment changed.
Another dependency is the reinvestment assumption. If you reinvest distributions at the same yield you started with, the math works better than it does in real markets. When rates fall, new purchases may yield less, and when rates rise, existing bonds may lose value before you can reinvest. This is why two portfolios with the same current yield can behave very differently across rate cycles.
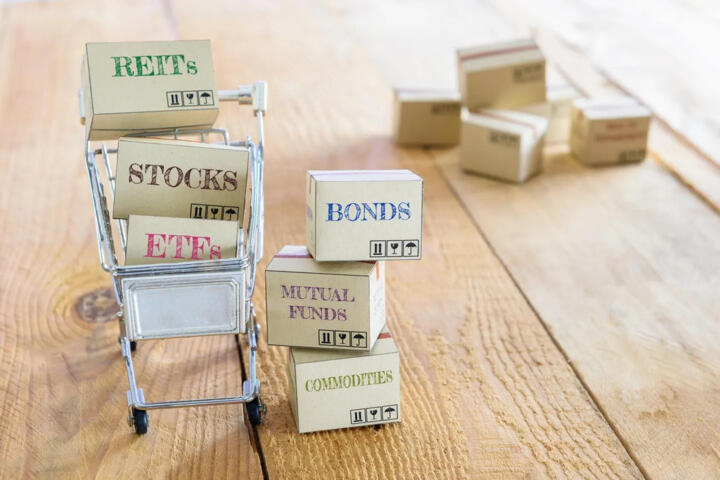
Finally, “income” depends on the asset mix. Equity dividends depend on earnings and payout policies. Bond coupons depend on credit quality and interest-rate levels. Preferred dividends depend on issuer terms and market spreads. Each source has different failure modes, and those modes show up at different times.
How To Think About 4% Yield
Build For Stability First
A 4% yield scenario is often achievable with a diversified mix that leans toward higher-quality bonds and/or broad equity exposure with a history of paying dividends. The key is that you are not trying to “manufacture” yield through the most stressed credit segments. In a 4% target, the portfolio’s job is to produce cash with a lower chance of forced selling during downturns.
Practical steps: start with a written withdrawal plan that states whether you will sell shares during drawdowns. If you plan to withdraw regardless of market conditions, you need a cash buffer or a bond sleeve designed for liquidity. A common approach is to hold a portion in short-duration instruments so that you can fund spending without selling longer-duration assets at depressed prices.
Tools and methods: use fund factsheets to check duration, credit quality, and distribution history. For bond funds, look at yield measures and the credit rating breakdown, then compare them to your risk tolerance. If you track performance, separate “income received” from “NAV change,” because they can move in opposite directions.
Realistic outcomes: a 4% distribution target can still experience years where total return is lower than the cash rate due to price declines. The goal is to reduce the frequency and magnitude of those gaps, not to eliminate them.
Stress Test The Withdrawal Path
For a 4% scenario, the main risk is not only that income drops, but that you sell assets at the wrong time. A simple stress test can be done without advanced software: pick a historical period with falling bond prices or equity drawdowns, then simulate withdrawals using a conservative sequence. If you withdraw 4% of the initial portfolio value annually, the portfolio may need to earn more than 4% to avoid shrinking.
Use a “cash-flow waterfall” view. First, estimate expected distributions. Next, estimate how much you must sell to cover any shortfall. Then, apply a haircut to distribution growth assumptions, because dividend growth is not guaranteed and bond coupons can be replaced at different yields. This is where many spreadsheets break, because they assume distribution growth stays smooth.
As a minor aside, I’ve found that using a monthly time step in the simulation catches timing effects that annual models miss, especially for bond funds that pay distributions on a schedule.
How To Think About 6% Yield
Accept More Credit And Rate Risk
A 6% yield scenario usually requires taking on more sensitivity to credit spreads, duration, or both. That can mean a higher allocation to intermediate-term bonds, higher-yield credit, or dividend-oriented equities with less stable payout growth. The portfolio can still be diversified, but the distribution rate is more likely to fluctuate.
Practical steps: map your target yield to the likely sources. For example, if you use bond funds, check whether the yield comes from higher credit risk (lower ratings or spread exposure) or from longer duration (rate sensitivity). If the yield is mostly spread-driven, you should expect distribution pressure during credit events. If it is mostly duration-driven, you should expect NAV volatility when rates move.
Tools and methods: compare the fund’s distribution yield to its total return over multiple periods, not just the trailing yield. Also check whether the fund’s distributions have been supported by realized gains, which can be a temporary effect. Morningstar and similar data providers publish metrics, but the most reliable source is the fund’s own holdings and distribution policy notes.
Realistic outcomes: a 6% cash target can be met in some years, but the probability of a multi-year period where total return trails the cash rate rises. Income may remain stable while principal declines, or income may decline after credit spreads widen.
Use Rebalancing Rules That Match Reality
Rebalancing is not a magic fix, but it can reduce the chance that you end up with unintended risk. A rule like “rebalance when an asset sleeve drifts by more than 20% of its target weight” can prevent a high-yield sleeve from dominating after a rally. The trade-off is that rebalancing can force sales at inconvenient times, so the rule should be paired with a withdrawal plan.
For a 6% scenario, consider separating liquidity from yield. Keep a portion in shorter-duration holdings for near-term spending, and let the higher-yield sleeve be the one that absorbs volatility. This separation helps you avoid selling the riskiest assets during the exact periods when their yields have already widened.
As an aside, I’ve seen investors set a “rebalance quarterly” rule and then ignore taxes. If you hold taxable accounts, tax lot selection and capital gains timing can matter more than the rebalance frequency.
How To Think About 8% Yield
Treat 8% As A Risk Budget
An 8% yield scenario typically implies meaningful exposure to credit risk, equity dividend risk, or both. Some investors reach 8% by combining high-yield bonds, preferred securities, or equity income strategies that can cut payouts during stress. The portfolio may show a high distribution rate, but the distribution can be supported by factors that do not persist.
Practical steps: require a written explanation for where the 8% comes from. If the yield is concentrated in lower-rated credit, you should expect higher default risk and wider spreads in downturns. If the yield is concentrated in equity dividends, you should expect payout variability tied to earnings and management decisions. If the yield is concentrated in covered call or option-income strategies, you should check how distributions relate to option premiums and whether the strategy caps upside.
Tools and methods: check credit quality distribution, call features, and the fund’s total return behavior during past spread-widening periods. Also examine whether the fund’s distributions include return of capital. In taxable accounts, return of capital can defer taxes but it can also signal that the distribution is not fully funded by income.
Realistic outcomes: an 8% cash target can occur, but the probability of a drawdown that forces you to sell increases. The portfolio’s “income” may look stable until it is not, and the timing of that change can be unpleasant.
Plan For Distribution Cuts And NAV Drops
For 8% yield, you should plan for at least one of these events: a dividend cut, a bond coupon reduction due to defaults or refinancing at lower yields, or a NAV decline that reduces the value of future income. A practical approach is to set a “minimum income floor” and a “maximum withdrawal” rule. If distributions fall below the floor, you reduce withdrawals or pause spending growth.
Another practical step is to diversify across income mechanisms. A portfolio that relies on one source—like a single high-yield bond fund—can fail in one direction. Diversifying across credit quality bands and duration buckets can reduce the chance that one macro event drives the entire distribution profile.
As a small detail, if you use a bond ladder, check the reinvestment schedule and the credit quality of each rung. A ladder that starts with high yields can still end up with lower yields after maturities if credit spreads compress or if your ladder includes issuers whose credit quality deteriorates.
Educational Case Examples
Scenario A: 4% For Spending
An investor with a taxable account targets 4% annual cash flow for living expenses. They allocate 60% to intermediate high-quality bond funds and 40% to broad equity funds with a dividend focus. They keep 12 months of spending in a short-duration sleeve so they do not sell longer-duration holdings during drawdowns. Over a year when rates rise, bond NAV declines, but distributions cover most spending; the investor monitors total return and adjusts withdrawals if the portfolio value drops materially.
The lesson is not that the yield “held,” but that the withdrawal plan prevented forced selling. The investor also checks distribution composition, because a bond fund can show a stable distribution while total return is negative.
Scenario B: 6% With Credit Spread Risk
A different investor targets 6% and accepts higher volatility. They allocate 35% to intermediate-term investment-grade bond funds, 35% to high-yield bond funds, and 30% to dividend-oriented equity funds. During a credit spread widening period, the high-yield sleeve’s NAV drops and distributions become less reliable. The investor follows a rebalancing rule that reduces the high-yield sleeve back toward target weights after rallies, and they pause discretionary spending when distributions fall below plan.
The lesson is that the portfolio’s cash rate is tied to credit conditions. The investor tracks both distribution yield and credit quality changes in the holdings, because the “headline yield” can stay high while risk increases.
Yield Comparison Checklist
| Scenario | Typical Risk Sources | What To Check In Factsheets | Withdrawal Behavior |
|---|---|---|---|
| 4% Yield | Duration risk, equity dividend variability | Duration, credit quality, distribution history vs total return | Prefer liquidity buffer; sell less during drawdowns |
| 6% Yield | Credit spread risk, higher rate sensitivity | Credit rating mix, spread exposure, distribution composition | Rebalance rules; reduce spending if distributions drop |
| 8% Yield | Higher default risk, payout cuts, option-income caps | Default sensitivity, call features, return of capital, total return in stress | Plan for distribution cuts and NAV drawdowns |
Step-by-step checklist you can use before committing to a yield target:
- Write the spending rule: the percentage you withdraw and whether you withdraw during drawdowns.
- Separate liquidity from yield: set aside near-term spending in short-duration holdings.
- For each holding, identify the main driver of yield (duration, credit spreads, dividend policy, or strategy mechanics).
- Compare trailing yield to multi-year total return, not just the last 12 months.
- Check distribution composition for return of capital or realized gains support.
- Run a stress test using a historical period with adverse rates or credit spreads.
- Set a “distribution shortfall” plan: what you do if cash flow falls below target.
Common Mistakes That Mislead
One mistake is chasing yield without checking whether it is funded by income or by return of capital. A distribution that includes return of capital can reduce your cost basis and may signal that the portfolio is not generating enough income to sustain the payout at the same rate.
Another mistake is using a single metric from a marketing slide. Trailing yield alone ignores NAV volatility and the possibility of distribution cuts. A portfolio can show a high yield while its total return is negative, which matters when you withdraw.
Investors also underestimate tax friction. In taxable accounts, interest and short-term gains can be taxed differently than qualified dividends, and bond fund distributions can include ordinary income. If you ignore taxes, a “6% yield” can become a lower after-tax cash flow, and the gap can widen across years.
A final mistake is assuming reinvestment at the same yield. When rates change, new purchases yield different amounts, and the portfolio’s future cash flow can drift away from the original target.
FAQ
Is Yield The Same As Total Return?
No. Yield measures cash distributions, while total return includes price changes. A portfolio can pay a high yield while losing value, which reduces future purchasing power.
How Can A 6% Portfolio Still Lose Money?
Bond and credit holdings can decline in price when interest rates rise or credit spreads widen. Distributions may not offset the NAV drop, so total return can be negative even with steady cash flow.
What Does Return Of Capital Mean?
Return of capital is a distribution that reduces your cost basis rather than being treated as income. It can defer taxes, but it can also indicate the distribution is not fully funded by earnings or interest.
Should I Use A Bond Ladder For Income?
A ladder can reduce reinvestment timing risk and provide liquidity at maturity dates. You still need to assess credit quality of each rung and accept that yields at reinvestment may differ from the original rate.
How Do Taxes Change Yield Targets?
After-tax cash flow depends on whether distributions are taxed as ordinary income, qualified dividends, or capital gains. The same headline yield can produce different spending power across tax brackets and account types.
Author's Insight
Income portfolios are best evaluated through cash-flow sustainability, not a single yield number. A 4% scenario can be consistent with higher-quality assets and a withdrawal plan that avoids forced selling. A 6% scenario usually requires more credit or duration risk, so distribution stability depends on spread and rate conditions. An 8% scenario often reflects risk that shows up during stress, so the investor’s plan for distribution cuts and drawdowns matters as much as the current yield.
Because product details vary by fund and share class, readers should verify duration, credit quality, and distribution composition directly in the latest factsheet and tax documents. If you want a tighter estimate, run a scenario analysis using at least one adverse historical period and include taxes for your account type.
Key Takeaways
- Yield is cash flow; total return includes price changes, so yield targets can mislead without NAV and tax context.
- 4% targets usually rely on higher-quality income sources and a liquidity buffer for withdrawals.
- 6% targets typically require more credit spread and/or duration risk, which increases the chance of income variability.
- 8% targets usually imply higher stress sensitivity; plan for distribution cuts and drawdowns before you commit.
- Use a checklist: identify yield drivers, verify distribution composition, compare to total return, and stress test the withdrawal path.